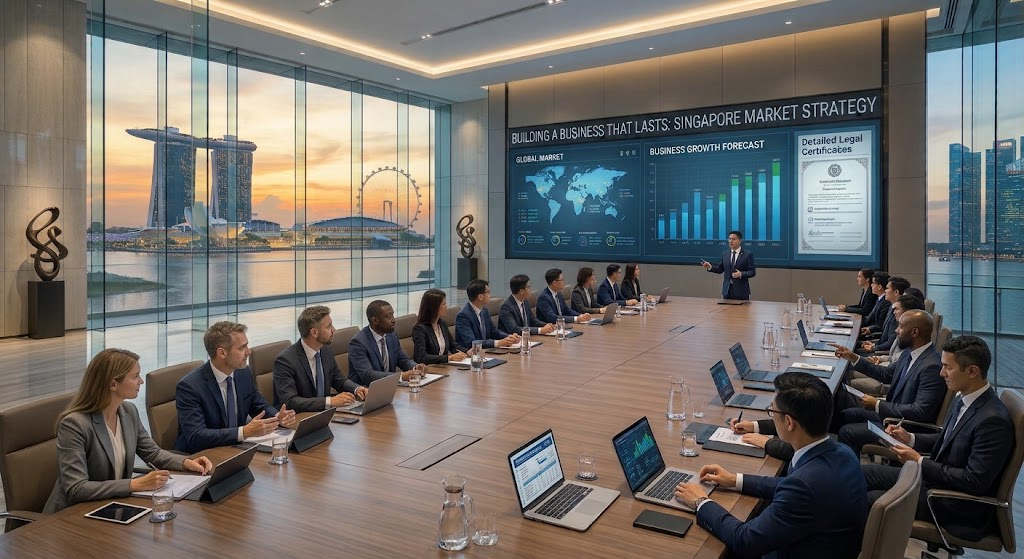
Entering a new business market is an exciting opportunity, but long-term success rarely comes from enthusiasm alone. Entrepreneurs must understand the local commercial environment, identify customer needs, prepare a realistic financial plan, and establish operations that can adapt as the business grows. Singapore has become an attractive destination for international entrepreneurs because of its developed infrastructure, strategic location, skilled workforce, and business-friendly environment. However, building a sustainable company requires careful preparation beyond simply completing the legal formalities.
For investors and business owners considering setting up a company in singapore, the most important decisions often happen before the first customer arrives. From selecting the right business model to understanding regulatory responsibilities, every early choice can influence the organisation’s future. A thoughtful approach helps entrepreneurs avoid unnecessary complications and establish a foundation that supports steady development.
1. Understand Singapore’s Business Environment
Before entering any market, entrepreneurs should examine the economic conditions and commercial opportunities available. Singapore has a diverse economy with established industries such as finance, technology, logistics, professional services, healthcare, manufacturing, and international trade.
Its location in Southeast Asia also makes it a useful base for companies seeking relationships with customers and suppliers across the region. Businesses can benefit from established transport networks, international connectivity, and access to a developed financial ecosystem.
However, a strong national economy does not guarantee success for every business. Entrepreneurs should examine their specific industry, target customers, competitors, and expected demand.
Market research should answer practical questions:
- Who are the potential customers?
- What problems does the proposed product or service solve?
- Which competitors already serve the market?
- How much are customers willing to pay?
- What makes the business different from existing alternatives?
These questions help determine whether the opportunity is commercially realistic before significant resources are committed.
2. Choose a Business Model That Can Grow
A business model explains how an organisation creates value, delivers products or services, and generates revenue. Selecting the right model is one of the most important decisions for an entrepreneur entering Singapore.
Some companies operate through direct sales, while others use subscriptions, online platforms, consultancy agreements, distribution arrangements, or business-to-business contracts.
The ideal approach depends on the target market and available resources. For example, a technology startup may generate recurring revenue through subscriptions, whereas a trading business may depend on supplier relationships, inventory management, and transaction volumes.
Entrepreneurs should also consider whether their model can expand without increasing costs at the same rate as revenue. A business that relies entirely on the founder’s personal involvement may struggle when customer demand increases.
Building scalable processes from the beginning can make future expansion easier and more manageable.
3. Select the Most Suitable Legal Structure
Choosing a legal structure affects ownership, liability, taxation, reporting responsibilities, and the way a company operates.
Singapore offers several business structures, including sole proprietorships, partnerships, limited liability partnerships, and private limited companies. Each has different legal and administrative characteristics.
A private limited company is often considered by entrepreneurs who want a separate legal entity with shareholders and limited liability, subject to applicable legal exceptions. It can also provide a structured framework for bringing in investors and expanding ownership.
However, the most appropriate structure depends on the nature of the business, the number of owners, financial arrangements, and long-term objectives.
Foreign entrepreneurs should pay particular attention to local incorporation requirements. For example, a Singapore company generally needs at least one director who ordinarily resides in Singapore. It must also appoint a qualified company secretary within six months of incorporation.
Understanding these requirements before proceeding can help avoid delays and unsuitable ownership arrangements.
4. Prepare a Realistic Financial Plan
A promising business idea needs a financial structure capable of supporting its operations. Entrepreneurs should estimate the initial investment, recurring expenses, expected revenue, and amount of working capital required.
Initial costs may include registration fees, professional services, equipment, software, office arrangements, marketing, and employee recruitment.
Ongoing expenses may involve salaries, rent, insurance, accounting, technology subscriptions, transportation, and regulatory compliance.
It is also important to calculate how long the business can operate before generating sufficient income. This period is often referred to as the runway.
A practical financial plan should include different scenarios:
- Optimistic scenario: Customer demand develops faster than expected.
- Expected scenario: Revenue grows gradually according to the business plan.
- Conservative scenario: Sales take longer to develop while operating costs continue.
Preparing for less favourable conditions can prevent cash-flow difficulties during the early stages of operation.
5. Understand Licensing and Industry Regulations
Registering a company does not automatically provide permission to conduct every type of commercial activity. Certain industries in Singapore require additional licences, approvals, or regulatory permissions.
For example, businesses operating in financial services, food and beverage, education, healthcare, and employment services may face industry-specific requirements.
Entrepreneurs should identify the relevant authorities and determine whether their planned activities require licensing before launching operations.
They should also consider employment rules, data protection responsibilities, consumer protection requirements, and any other regulations relevant to their business model.
Ignoring these requirements can lead to operational restrictions, financial penalties, or delays.
A regulatory checklist prepared before launch can help business owners identify obligations and allocate sufficient time to complete them.
6. Build the Right Banking and Accounting Arrangements
Financial organisation should begin before a business starts handling significant transactions. Entrepreneurs need reliable systems for receiving payments, paying suppliers, managing expenses, and monitoring cash flow.
Opening a corporate bank account can help separate business transactions from personal finances. However, account approval depends on the financial institution’s due diligence procedures and its assessment of the company’s ownership, activities, and documentation.
Accounting arrangements are equally important. Businesses should maintain accurate records of income, expenses, invoices, receipts, and other financial transactions.
Singapore companies also need to understand their tax obligations. The standard corporate income tax rate is 17%, although applicable exemptions and incentives may reduce the effective tax payable for eligible businesses.
Depending on turnover and other circumstances, a company may also need to consider Goods and Services Tax registration.
Working with qualified accounting professionals can help establish suitable reporting procedures and reduce the risk of financial errors.
7. Develop a Strong Market Entry Strategy
Even a well-structured company needs customers to survive. Entrepreneurs should develop a market entry strategy that explains how the business will introduce its products or services and build a customer base.
For some organisations, digital marketing and search engine visibility may be the most effective starting points. Others may benefit more from industry networking, direct sales, trade events, or strategic partnerships.
A strong strategy should clearly communicate the value offered to customers. Instead of focusing only on product features, businesses should explain how their solutions address specific problems.
Companies should also establish realistic customer acquisition targets and monitor the performance of their marketing activities.
Testing different channels on a smaller scale can reveal which approaches produce the best results before larger budgets are committed.
8. Recruit the Right People and Establish Clear Responsibilities
Employees can significantly influence the quality and consistency of business operations. However, hiring too quickly can increase costs before the company has established stable revenue.
Entrepreneurs should identify the roles that are essential during the initial stage and distinguish them from positions that can be introduced later.
Clear job responsibilities, performance expectations, and communication procedures help prevent confusion as the team expands.
Companies hiring in Singapore must also understand applicable employment requirements, including work pass conditions where foreign employees are involved.
A carefully planned recruitment strategy allows the business to develop its capabilities without creating unnecessary financial pressure.
9. Build Compliance into Everyday Operations
Long-term business stability depends on more than completing incorporation procedures. Singapore companies must continue meeting their statutory and administrative obligations after establishment.
These may include maintaining company records, filing annual returns, updating relevant information with the Accounting and Corporate Regulatory Authority (ACRA), and fulfilling tax reporting responsibilities.
Companies must also maintain appropriate corporate governance procedures. Board decisions, shareholder matters, director appointments, and changes in ownership should be documented correctly.
For entrepreneurs setting up a company in singapore, establishing reliable compliance procedures early can make future administration considerably easier.
A compliance calendar, organised document storage, and professional advisory support can help business owners monitor their responsibilities throughout the year.
10. Plan for Expansion Before It Becomes Necessary
A business that succeeds in its initial market may eventually consider regional expansion, additional investment, new product lines, or strategic partnerships.
These opportunities should be considered during the planning stage, even if implementation is expected to happen later.
For example, entrepreneurs should think about whether their ownership arrangements can accommodate future investors and whether their operational systems can support a larger customer base.
They should also review their financial structure regularly and identify areas where additional investment may be needed.
Planning for growth does not mean expanding as quickly as possible. Sustainable expansion requires evidence of customer demand, sufficient resources, and an operating model that can support increased activity.
Conclusion
Building a lasting business in Singapore requires more than a promising idea and successful incorporation. Entrepreneurs must understand the market, select an appropriate legal structure, prepare realistic financial projections, meet industry requirements, and develop effective customer acquisition strategies.
They should also establish reliable accounting procedures, recruit carefully, and maintain corporate compliance throughout the company’s development.
For anyone considering entering this competitive market, preparation is one of the most valuable investments. By making informed decisions before launching operations, entrepreneurs can reduce avoidable risks and create a business structure capable of adapting to changing commercial conditions.
Ultimately, setting up a company in singapore should be viewed as the beginning of a longer business journey. The real objective is not simply to establish a legal entity, but to build an organisation that can serve customers, manage its responsibilities, and grow sustainably over time.